
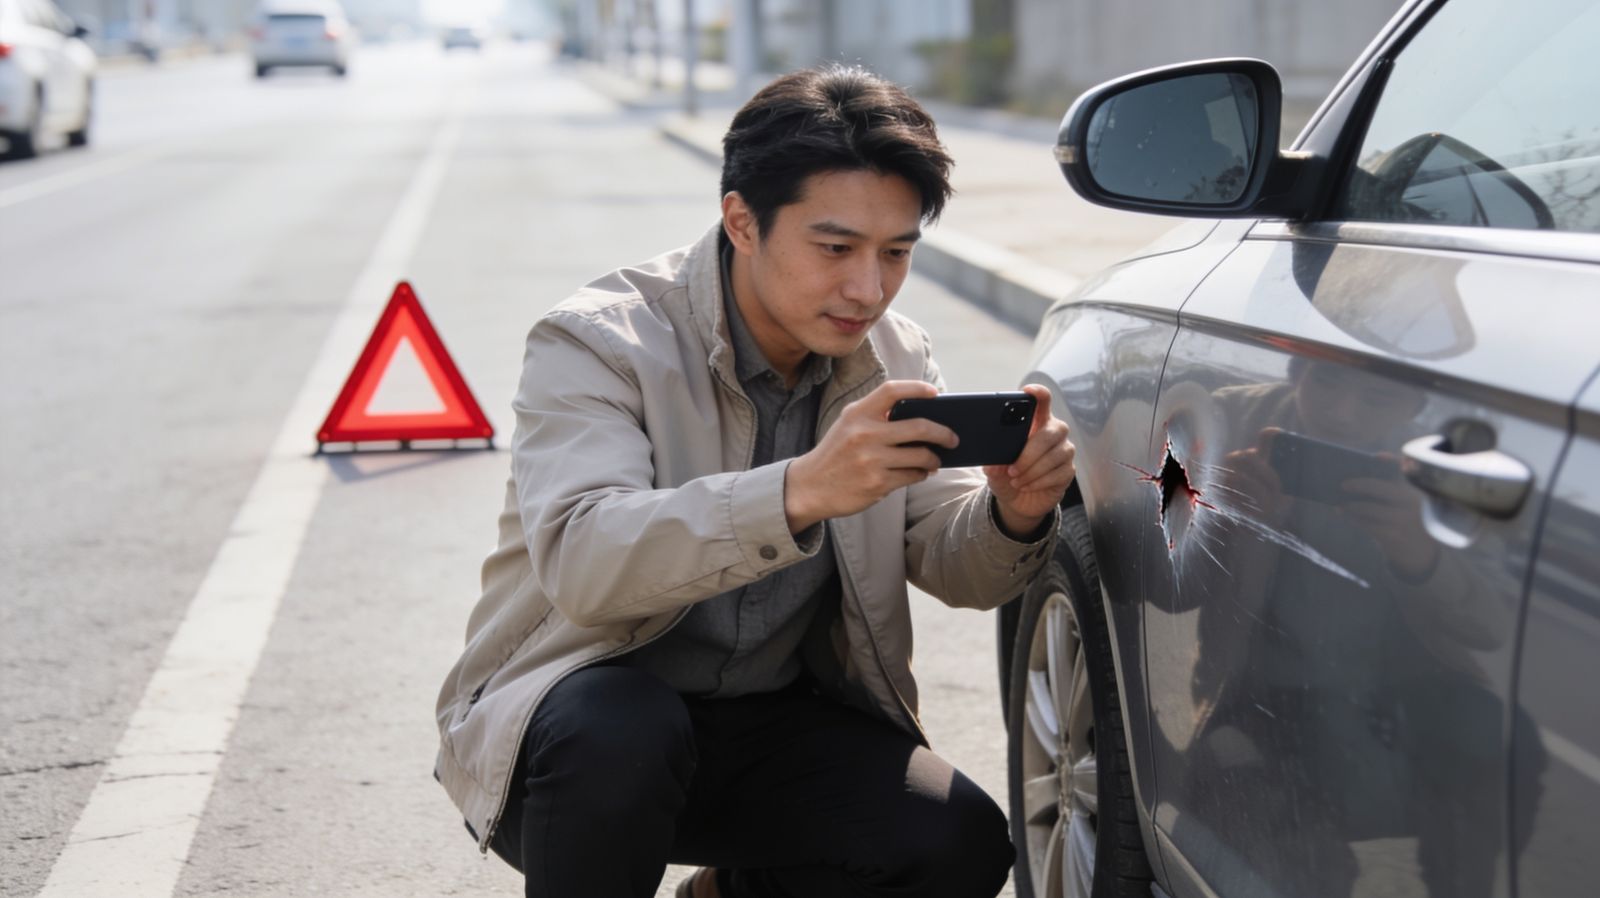
What should you prioritize in the first few minutes?
In every loss, the priority is people's safety. If there is injury, fire, a gas leak or a structural hazard, first call the 112 Emergency Call Center and make the area safe. Insurance formalities come after this stage.
Once safety is ensured, take reasonable measures to keep the damage from getting worse: shutting off the water, turning off the electricity, temporarily covering broken glass or moving the vehicle to a safe spot where it does not block traffic. The general conditions of insurance expect the insured to take reasonable measures to minimize the loss; the costs of these measures are also assessed according to the policy terms.
How should you document the loss?
Until the loss adjustment is carried out, images of the damaged area are the strongest basis for your claim. Photograph the damage from different angles and take short videos. Do not throw away damaged items; if possible, keep them in a separate place.
- Wide shots and close-up photos
- The source of the damage (burst pipe, broken lock, point of impact)
- Make and model details of damaged items and devices
- Invoices, warranty documents and purchase records, if available
- Witness details and a short written summary of the incident
Which official records may be required?
Depending on the type of loss, an official report or record may be an essential document in the insurance file. Creating these records at the scene and in good time prevents problems of proof later on.
- Traffic accident: If there is only property damage, the parties can complete the accident report form together; the report can also be created via e-Devlet (e-Government). If there is injury or death, or if the parties cannot agree, the police or gendarmerie must be notified.
- Theft: A report should be filed at the nearest police station or gendarmerie.
- Fire: A fire department report should be obtained for the file.
- Earthquake: Building damage covered by compulsory earthquake insurance is reported to the Turkish Catastrophe Insurance Pool; for contents and other cover, a separate claim is made under your home or commercial policy.
- Flooding and damage from a neighbor's property: It is helpful to assess the situation together with the building management and the neighbor.
How and when should a claim be reported?
The Turkish Commercial Code and the general conditions of insurance require the insured to notify the insurer without delay after learning that the insured event has occurred. The general conditions of some lines of insurance also set a specific deadline in days for this notification. That is why reporting the loss without waiting, as soon as you learn of it, is the safest course.
If your policy was arranged through a broker, you can report the loss directly to your broker; the broker follows up the opening of the file with the insurance company and the appointment of the loss adjuster. When reporting, have ready the policy number, the name or company name of the insured, the date and place of the loss, how it occurred, the estimated amount of the loss, and the full address and contact details for the loss adjustment.
If you reported the loss by phone, sending the same information by e-mail and noting the file number you are given will make all subsequent correspondence easier. If more than one policy covers the same loss, for example if you have both a home policy and a compulsory earthquake insurance policy, a separate notification may need to be made to each.
What should you watch out for during the loss adjustment process?
The insurance company may appoint an independent loss adjuster to determine the cause and amount of the loss. Do not start repairs or cleanup before the loss adjuster's inspection is complete, except for urgent measures to keep the damage from getting worse. If you have to take urgent action, be sure to document the situation before and after.
Be present during the loss adjuster's visit, explain the damage and how the incident unfolded clearly, and list the documents requested. If you see an item in the loss adjuster's report that does not reflect the actual loss, you can exercise your right to object. Where no agreement can be reached, the options include applying to the Insurance Arbitration Commission or taking legal action.
What can you do to speed up the claims process?
The time it takes for a claim to be paid depends on the type of loss and the completion of the file. The most common cause of delays is missing documents. The following practices help the file progress smoothly:
- Send the requested documents in one go and in full.
- Keep the quotes and invoices obtained for repairs.
- For commercial losses, keep stock, fixed asset and accounting records ready.
- Respond promptly to requests from the insurance company or your broker.
- Keep all correspondence and the file number on record in one place.
Frequently Asked Questions
Should I report a minor loss?
This depends on your policy's deductible, your no-claims discount and the amount of the loss. Covering a minor loss yourself can sometimes be more advantageous at renewal. However, if the damage may get worse later or the other party is making a claim, it is safer to report it. Consult your broker before deciding.
Water from my neighbor's apartment damaged my home. What should I do?
First, have the source of the water identified, stop the flow and photograph the damage. Then report the loss under your own home policy. Once your insurer has covered your loss according to the policy terms, it may seek recovery from the responsible party if necessary. Your neighbor's liability cover may also become part of the process.
Can I take my car to the repair shop right after an accident?
You can move the vehicle to get it to a safe place; however, before starting repairs you should report the claim and wait for the loss adjustment. Check the contracted repair shop conditions of your car insurance policy. If repairs are carried out before the loss adjustment, it may become harder to assess the damage.
What can I do if the insurance company rejects my claim?
First, ask for the reason for the rejection in writing and compare it with the policy terms. If the reason is not justified, you can object to the insurance company. If no agreement is reached, you can apply to the Insurance Arbitration Commission or to the courts. If you work with a broker, the broker prepares the objection on your behalf.
Istanbul Insurance expert team · Last updated: November 2026 · Reviewed by our technical team.